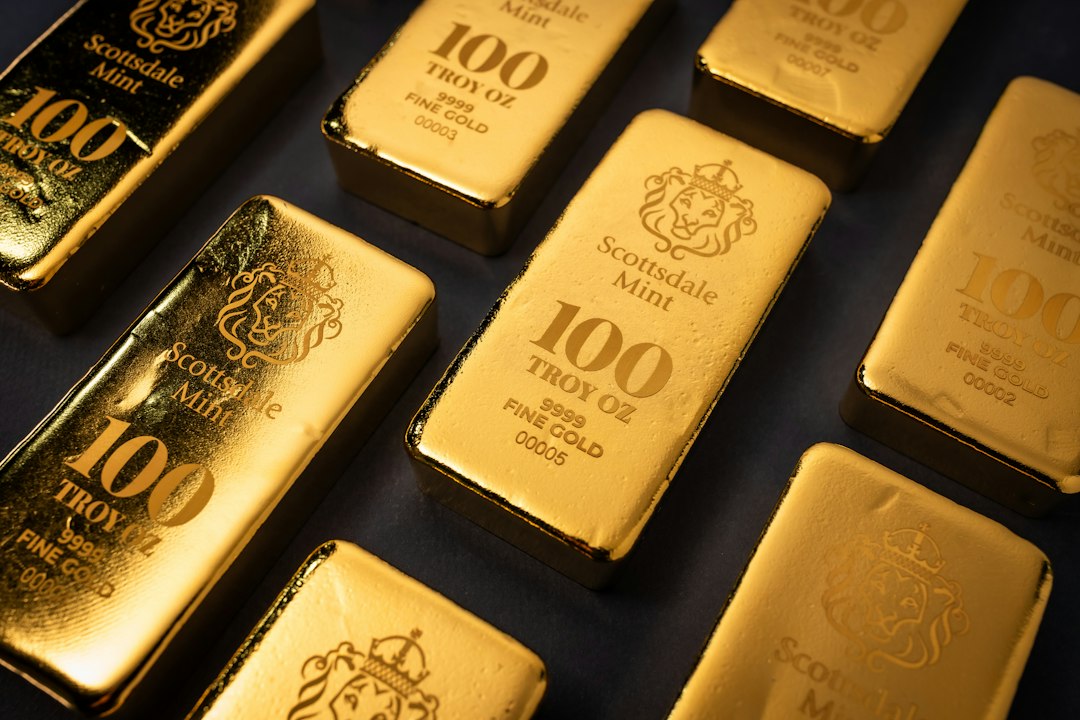
A coin rests in your hand, while an ETF share appears as a line in your brokerage account. Those choices offer different ways to get exposure to precious metals, and the difference matters when you need access to your money. Holding a physical item means planning where to keep it and how to protect it.
Fund shares can be simpler to trade, but they involve fees and financial systems. Taxes, liquidity, and risk can also affect how well either option fits your investment goals and risk tolerance. The right choice depends on what you want metal to do in your portfolio and which trade-offs you can accept. You’ll find a practical comparison, starting with the basic question: what does each option let you own?
Bullion, Coins, or ETFs: What Are You Actually Buying?
You can own precious metal itself, or you can own shares in a fund that holds or tracks metal. That distinction shapes your rights, custody arrangements, and access to the investment.
The spot price is the current market price for one troy ounce of unprocessed precious metal, before product premiums and other costs. A premium is the extra amount you pay above spot price for a physical item.
Physical bullion comes as bars and coins
Investment-grade bullion is metal sold in bars or coins, often with stated weight and purity. You can buy physical bullion from a dealer online or in person.
A gold bar or coin is a specific item. You can keep it yourself or arrange storage, including allocated storage, where a vault identifies metal held for you rather than showing only a general account balance.
An ETF share is a claim on a fund
A gold ETF share represents an interest in a fund or trust that holds gold, not direct ownership of a particular coin or bar. Investors can generally buy ETF shares through a brokerage account.
A physically backed fund may hold bullion in custody, while its shareholders usually do not own specific pieces. In the bullion, coins, or ETFs choice, that means fund shares offer metal exposure through a financial product.
| Option | What the investor owns | Common form | Main custody arrangement |
|---|---|---|---|
| Gold bar | A specific physical bar | Bar | Investor or chosen vault |
| Sovereign-mint coin | A specific physical coin | Coin | Investor or chosen vault |
| Gold ETF | Fund shares | Exchange-traded shares | Fund-arranged custody |
Physical ownership still leaves a choice between bars and coins. Their size, design, and pricing can change the shopping and handling experience.
How Do Gold Bars and Sovereign-Mint Coins Differ?
A compact bar may suit you if you want metal exposure in a simple form. A widely recognized government-mint coin may suit you if familiar designs matter more. Neither format is automatically the better investment.
Both formats contain a stated weight and purity, while design, packaging, size, recognition, and dealer pricing can differ. Compare the exact item, not just its general category.
Gold bars prioritize metal content and compact storage
Gold bars come in cast and minted forms, with size and finish varying by product. Brands include PAMP Suisse, Perth Mint, Argor-Heraeus, Asahi, and Valcambi.
Bars can offer a direct way to buy a stated amount of metal. Their packaging and markings may differ, so check the product details and keep any assay card or sealed packaging that comes with the item.
Sovereign-mint coins add government-issued identity
A sovereign-mint coin is a government-issued bullion coin. Examples include American Eagles, Canadian Maple Leafs, British Britannias, and South African Krugerrands.
A government-issued identity does not make every coin rare or collectible. Most buyers should distinguish standard bullion coins from special editions sold at prices tied to collector demand.
| Attribute | Gold bars | Sovereign-mint coins |
|---|---|---|
| Typical form | Cast or minted bar | Government-issued coin |
| Examples | PAMP Suisse or Perth Mint bars | American Eagle or Canadian Maple Leaf coins |
| Price considerations | Metal value plus product premium | Metal value plus premium that can reflect coin demand |
Dealer premiums, the amount paid above spot price, can vary for either format. Coin demand may affect the premium, so the advertised price does not show metal value alone.
The format affects what you shop for and how you handle the item. Your next practical choice is how to buy it and where to keep it.
How Do You Buy and Hold Each Option?
A first-time buyer might choose a small bar or an ETF share, then decide where the metal or account will stay. Make both choices before sending money, because a purchase plan should include custody.
Use a clear sequence: compare the seller or brokerage, check the product, arrange custody, and keep records. Terms vary by provider, so read the details that apply to your own order.
- Choose a reputable dealer or brokerage, then read its account, payment, and transaction terms.
- Compare the exact product details or ETF documents before you place an order.
- For physical metal, confirm delivery, custody, and insurance arrangements before paying.
- Save receipts, product details, serial numbers where available, and brokerage account records.
At home, a safe gives you direct access but leaves security to you. A bank safe-deposit box is held at a bank, while a private vault stores metal through a separate service.
With allocated storage, a vault sets aside specifically identified metal for a customer. That differs from a general account balance that does not identify particular pieces.
Provider fees, account minimums, customer-service details, and insurance terms vary. There is no single fee or insurance arrangement that applies to every buyer, so check the current terms directly.
These custody choices can create different ongoing costs. Comparing those costs requires more than looking at the metal’s quoted price.
What Costs Should You Compare Before Buying?

Two gold purchases can have different total costs even when their advertised prices look close. The lower headline price may not stay lower after fees and storage.
Compare the upfront price and each ongoing charge separately. Physical bullion and ETFs can both cost more than the underlying spot price.
The purchase price includes premiums and trading costs
A dealer adds a premium above spot price to a physical item. Physical bullion premiums are typically higher than ETF purchase premiums, but the exact amount can vary by product and dealer.
For shares, a brokerage may charge transaction fees, though charges depend on the account and its terms. The market price of an ETF share can also differ from the value of the gold exposure it represents.
These spot price premiums matter because the amount you pay includes more than the metal’s quoted market value. Ask what the listed price includes and whether other transaction costs apply.
Holding costs continue after the purchase
An ETF’s annual operating charge as a percentage of assets is its expense ratio. ETF management charges are often below 1% of investment value per year, but that figure is not a promise for every fund.
Check the current fund documents for its stated expense ratio. Even a small annual fee reduces the value left invested over time because charges continue to add up.
Physical metal may bring storage and insurance costs, depending on where and how you keep it. A self-storage choice can still involve costs for a safe, security, or added insurance.
Provider-specific prices, storage rates, and trading fees vary, so check live terms before you commit. No universal fee schedule applies across funds, dealers, and vaults.
A low-cost option can still be a poor fit if you cannot accept its selling or custody risks. Costs are only useful to compare when the way out also works for you.
How Quickly Can You Sell Each Option?
An unexpected bill may force you to turn an investment into cash. You can generally place an ETF sell order through a brokerage during market hours, while bullion usually requires finding a buyer. The sale path can affect timing.
ETF shares are often easier to trade quickly, but an exchange sale does not guarantee a particular price. A physical-metal sale may take longer, depending on the product and buyer.
- How quickly might I need the money?
- Which trading or dealer channel can I access?
- What spread, shipping, or settlement delay could affect the sale?
ETF shares can generally be bought or sold during market hours through a brokerage account. The trade price changes with the market, and order timing can affect the price you receive.
Physical bullion usually sells through a dealer or another established buyer. Timing depends on who will buy the item, the product, and the arrangements for delivery and payment.
Physical sales can also involve shipping or a visit to a buyer. A bar or coin does not turn into cash until a buyer agrees to the transaction and completes payment.
Think about liquidity risk, the chance that you cannot sell quickly at the price or time you want. The difference in sale paths comes from the risks built into each ownership structure.
What Risks Come With Each Choice?
Every choice can lose value or create practical problems, but the failure points differ. Physical metal brings hands-on custody concerns, while ETF shares rely on funds and account systems.
Neither an item’s familiar name nor an ETF label removes market risk or guarantees resale value. Prepare for the risks that come with the way you hold the investment.
Physical bullion brings custody and authenticity risks
You must protect physical bullion against theft, loss, and damage. Storage failure, such as losing access to a key or having an unsafe space, can also disrupt your plans.
Counterfeit risk matters when you buy or sell a bar or coin. A known brand or popular sovereign-mint coin is not proof that a specific item is genuine.
Allocated storage can reduce uncertainty about which metal a vault holds for you. It does not remove every operational risk or guarantee that you can access the metal whenever you want.
ETFs rely on financial and digital systems
ETF investors do not personally authenticate individual bars. Instead, they rely on fund disclosures and the companies involved in custody and administration.
Fund structure, market prices, and intermediary services can all affect your investment. Brokerage accounts also depend on digital systems, which can face cybersecurity threats.
Keep account access secure and review fund information rather than assuming a gold label tells the whole story. Physical custody and financial custody call for different checks.
Once you know which risks you can manage, consider the role you want precious metals to play in your portfolio. That role can shape how you think about diversification.
How Can Each Option Support Portfolio Diversification?
Gold bars, sovereign-mint coins, and ETFs may all add exposure to precious metals, but they do so through different structures. The right role depends on how you want that exposure to fit with other assets.
Precious metals do not generate interest or company earnings, and their value can rise or fall. Consider them alongside the rest of your portfolio, not as guaranteed protection.
| Option | Potential portfolio role | Access and custody | Main trade-off |
|---|---|---|---|
| Gold ETF | Price exposure | Brokerage trading | Financial intermediary dependence |
| Gold bar | Direct metal ownership | Self-arranged or vault custody | Storage and resale arrangements |
| Sovereign-mint coin | Direct metal ownership | Self-arranged or vault custody | Product premium and authenticity checks |
An ETF may help you add price exposure through an account you already use. Directly held metal gives you a tangible reserve, but also requires plans for custody and resale.
Portfolio diversification means spreading investments across different types of assets. It does not ensure a gain or prevent losses, and precious metals can still move in value.
Liquidity risk also matters: a holding that is hard to sell may not serve a goal that needs quick access to cash. Identify your goal first, then choose the product whose trade-offs match it.
What Should U.S. Investors Know About Taxes?

Tax treatment can differ by investment structure, so check the rules before you sell. A gain may be taxable, but the result depends on your specific situation and applicable rules.
The investment vehicle, holding period, account type, and current tax rules can all affect how a sale is treated. Do not assume every gold investment follows the same tax path.
A sale can create a taxable gain
If you sell an investment for more than your tax basis, the gain may have tax consequences. How the gain is treated can depend on what you owned and how long you held it.
Do not assume ETF gains are always taxed as ordinary income or that physical metal always receives a higher rate. Fund structures and current U.S. rules can differ.
Keep records of purchase dates, costs, sales, and related account details. Those records can help you or a tax professional review the result.
Account structure can change the details
Retirement-account eligibility and custody rules depend on the account and the arrangement. Not every account can hold every type of asset in the same way.
Tax-advantaged accounts have rules that can affect what you may hold and who can hold it. Review current IRS guidance before making a choice.
A qualified tax professional can help apply the rules to your circumstances. This overview is not individualized tax or legal advice.
Tax questions can change the appeal of a choice, but they do not define your whole decision. Match the structure to your goals and risk tolerance.
Which Option Fits Your Goals and Risk Tolerance?
One investor may want easy portfolio adjustments, while another may value direct possession of metal. Your main priority can point toward different choices, even when both investors want gold exposure.
Choose based on access, custody, and the risks you can accept, not on a promise that one form avoids price changes. Neither choice removes the risk that metal prices can fall.
Choose an ETF for convenient market exposure
An ETF may suit you if brokerage convenience and trading flexibility matter most. You can generally place orders through your account during market hours without arranging personal storage.
This structure can make portfolio changes simpler, but it still depends on a fund and financial intermediaries. Consider your comfort with online account access and the fund’s documents.
Consider physical metal for direct ownership
Physical bullion may suit you if you value tangible ownership and can manage security, authenticity, and resale. You decide where the item stays, or you arrange a vault service.
Your investment horizon matters, too. If you expect to need cash soon, consider how quickly you could sell and whether the sale process fits your timing.
Urgency of access can matter as much as comfort with custody. A product that suits a long-term holding may not fit a near-term cash need.
These goals do not have to be mutually exclusive. Some investors choose both forms, as long as the combined approach fits their circumstances.
How Do You Check an ETF or Bullion Seller?
A product page may advertise gold exposure without making custody or redemption clear. Pause before paying and check what the fund or seller actually offers.
Read the product terms before sending money, including how the fund holds metal or how the dealer handles an order. A familiar name is not a substitute for clear terms.
Review the ETF’s structure and documents
Start with the prospectus, the fund document that explains its structure, risks, fees, and other terms. Then check what the fund reports about its holdings and custody.
Many physically backed ETFs do not let ordinary shareholders take delivery of specific bullion. Any redemption rights can be limited, so do not assume you can exchange shares for a bar.
Check the dealer’s product and transaction terms
For either a fund or a dealer, focus on five checks before you commit:
- Read the ETF prospectus and identify the fund structure.
- Verify reported holdings, custody, and whether ordinary shareholders can redeem.
- Compare the stated expense ratio and trading terms.
- Confirm the dealer’s identity, product details, and authenticity documents.
- Read payment, delivery, return, and buyback terms before purchase.
For a physical item, compare its stated weight and purity with the listing. Ask what authenticity records come with the product and keep them after the sale.
There is no universal dealer buyback price or service guarantee. Review the terms for the exact seller and product, then watch for mistakes that could undo careful research.
What Buying Mistakes Should You Avoid?
A buyer who compares only advertised prices may miss the premium or the terms for selling later. That shortcut can make a purchase look cheaper than it is.
Read the full product and transaction terms before you commit, not just the price on the screen. Unfamiliar products, rushed decisions, and unverified sellers can raise the chance of costly errors.
- Judging only by spot price and ignoring premiums.
- Buying a collectible-priced coin while expecting bullion pricing.
- Failing to plan storage and insurance before taking delivery.
- Assuming ETF shares can be exchanged for a personal coin or bar.
- Overlooking sale, account, or tax terms that may affect your plans.
A listed spot price shows the metal’s market price, not necessarily the price of a physical item. The premium can affect what you pay, while dealer terms can affect what happens when you sell.
A collectible coin may carry a price based partly on its design or demand. If you want ordinary bullion exposure, compare its price with the metal content and product type.
Counterfeit risk can rise when you rely on an unfamiliar seller or skip product checks. Take time to confirm who is selling the item and what records support it.
Before buying, make sure you understand the account and sale terms, as well as any possible capital gains taxes. A clear plan can prevent avoidable surprises and leave room to consider more than one form.
Can You Own Bullion, Coins, and ETFs Together?
Yes, you can hold physical bullion and ETF shares together if the mix suits your circumstances. Each form can serve a different purpose without making the other one unnecessary.
Track your total metal exposure, fees, liquidity needs, custody, and tax records across all holdings. A combination does not guarantee diversification benefits or profit.
You might use ETF shares for price exposure through a brokerage account and keep bars or coins for direct ownership. That approach brings both the convenience of account trading and the work of holding physical items.
A combined portfolio can also mean more records and more than one set of terms to review. Track what you own, where it is held, and what each product costs to maintain.
Think about how much access you may need, where physical items would stay, and how comfortable you are with market and custody risks. The same combination will not fit every investor.
This approach does not come with a recommended percentage. Choose the mix based on your priorities, then confirm that each holding has a clear role.
Decide what job you want each holding to do before you add it. Your final choice should reflect your own priorities and capacity to manage the trade-offs.
Our Conclusion
Choose the ownership structure that suits the job you want precious metals to do. ETFs favor convenient market access, while physical bullion offers direct ownership.
The right balance depends on your purpose, time horizon, and ability to manage custody. Neither form removes the chance of price changes, so make sure its role fits your broader plan.
Before comparing a specific fund or dealer, write down the portfolio role you want, your cash-access needs, and the ongoing costs you can accept.
Our FAQs
Can I take delivery of the gold held by an ETF?
Usually, ordinary ETF shareholders cannot take delivery of specific gold bars. Shareholders generally own fund shares, while the fund or trust holds bullion through its custody arrangements. Some funds may have redemption provisions, but those rights can be limited or unavailable to individual investors. Read the prospectus and custody disclosures to see what the specific fund allows.
Do gold coins sell for more than their gold content?
Often, yes. Buyers commonly pay a premium above the coin’s spot value, and the amount can reflect product demand, dealer pricing, or collectible features. A standard bullion coin is not automatically rare, and its resale price may not match a special-edition coin’s asking price. Compare the coin’s weight, purity, and total price before buying.
Is a gold ETF backed by allocated gold?
It depends on the fund’s structure and custody arrangements. Check the prospectus and custody disclosures to learn whether the fund holds bullion and how it identifies or accounts for it. Fund-held gold does not mean each shareholder owns specific bars. Ordinary shareholders usually hold shares in the fund rather than direct title to individual pieces.
Can I sell part of a gold bar when I need cash?
No, a bar is generally sold as a whole item, so you cannot sell just a portion of that bar. If you want more flexible transactions, you might consider smaller denominations or ETF shares, which can be traded in individual units. Your sale options and timing still depend on the buyer, market, and transaction terms.
Does a home insurance policy cover gold bullion?
Do not assume a standard home policy covers bullion fully, or covers it at all. Check the policy’s limits, exclusions, and documentation rules, and ask whether separate coverage is needed. Requirements can differ by insurer and policy. Keep purchase records and details of the items, but confirm coverage with your insurer before relying on it.
Are gold bars or coins easier to authenticate?
Neither form is always easier to authenticate; the item and verification method matter. Use a reputable dealer and review the product’s stated weight, purity, and supporting records. Packaging or a familiar brand can help identify a product, but no name alone proves that a specific item is genuine. Ask how the seller handles authenticity concerns.
Can I hold physical gold in a retirement account?
It may be possible in some arrangements, but eligibility and custody rules depend on the account and the specific structure. Do not assume you can store retirement-account gold at home or move an existing holding without tax effects. Review current IRS guidance and speak with a qualified tax professional before choosing an account or arranging custody.
Explore Our Exciting Related Products and Services